Home / Solutions / Finance leaders
RoleWhat was awarded,
and what is actually funded
Two numbers that are frequently not the same, rarely tracked separately, and usually reconciled at the worst possible moment. Incremental funding is normal in government contracting and almost nothing tracks it properly.
Awarded is not funded
Under incremental funding an award can be agreed at one figure and funded at another, and the gap between them is where finance surprises come from.
Awarded is not funded
Under incremental funding an award can be agreed at one figure and funded at another, and the gap between them is where finance surprises come from.
- The funding gap is visible rather than discovered
- Commitment is visible before invoices arrive
- Detail and totals both available
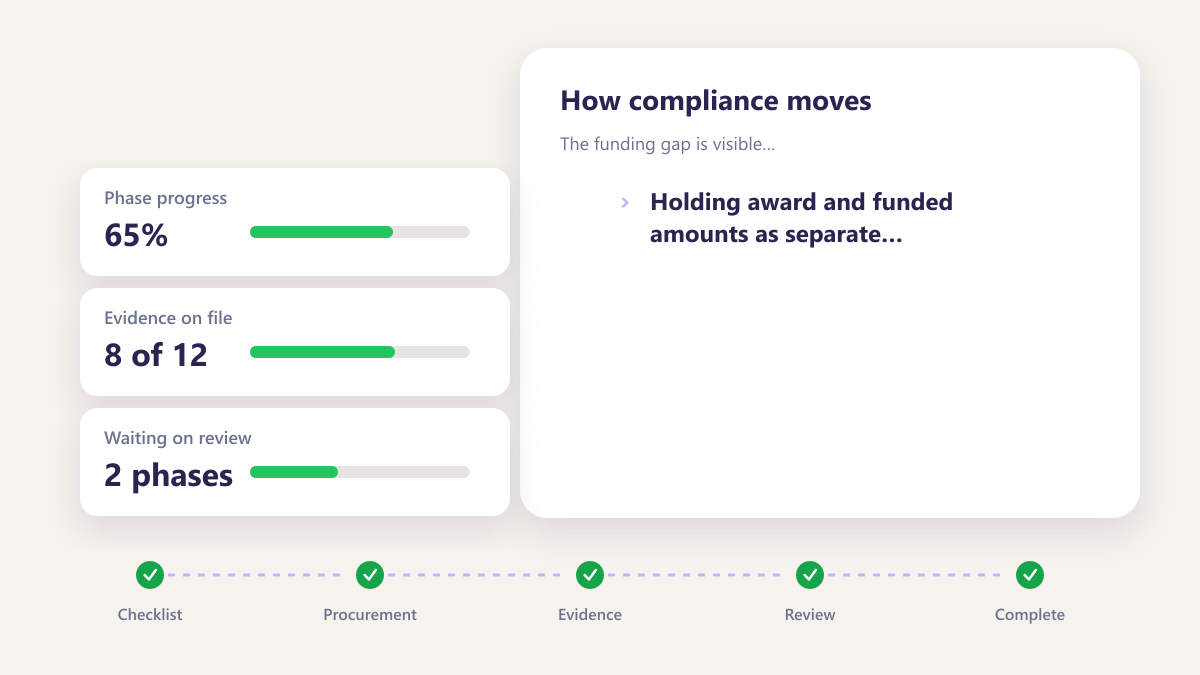
The funding gap is visible rather than discovered
Holding award and funded amounts as separate figures on each modification means the difference is something you can see at any point rather than reconstruct.
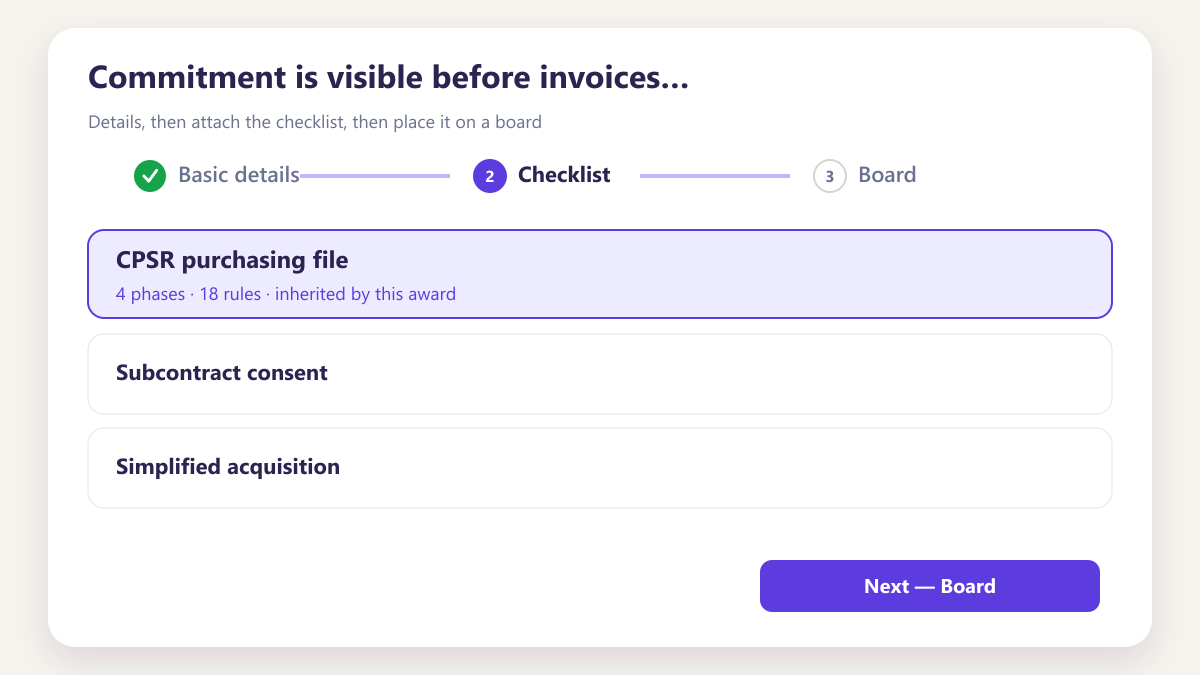
Commitment is visible before invoices arrive
An award placed is money committed. Seeing only invoiced actuals makes a budget look healthier than it is for as long as the invoicing lag lasts.
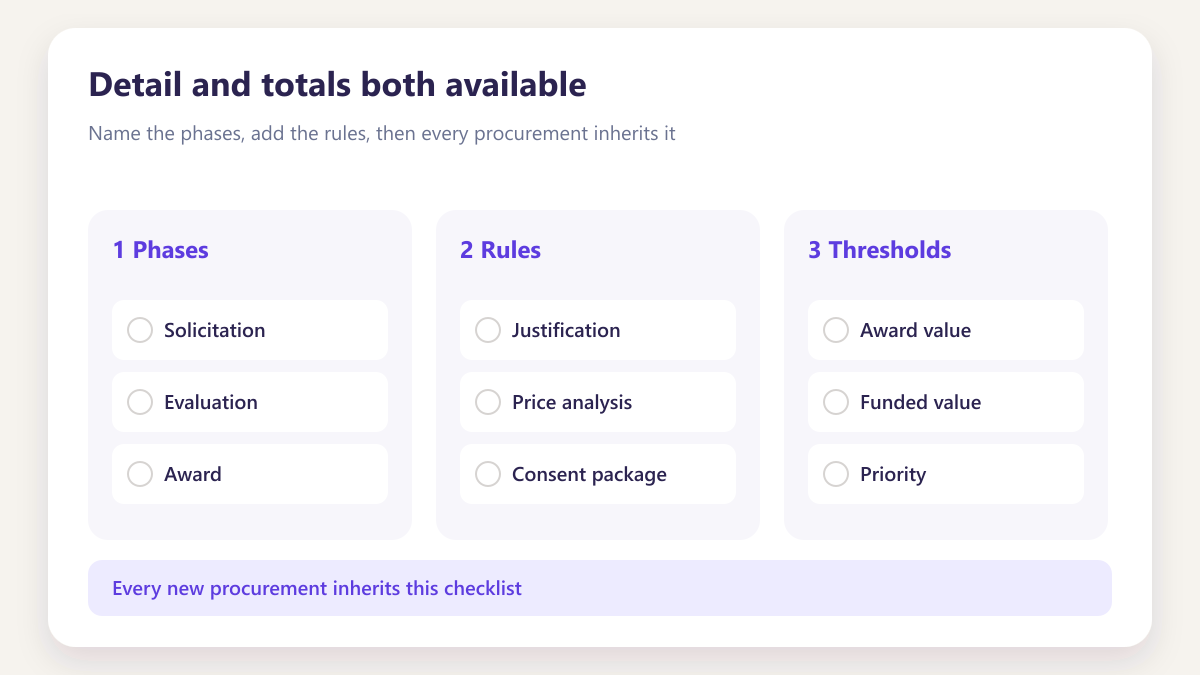
Detail and totals both available
Each modification carries its own two figures and the totals follow from them, so there is no reconciliation between a summary and the records underneath it.
How funding usually gets tracked
Most finance teams track this somewhere. The difficulty is that the somewhere is rarely connected to the award record.
Merged into one
Award and funded amounts get recorded as a single number, which works until incremental funding means they differ and nobody can say by how much.
Held separately
Both figures sit on each modification, so the gap is a value you can read rather than a calculation somebody has to perform.
Only actuals
The budget shows what has been invoiced, so a quarter with a long invoicing lag looks considerably healthier than it actually is.
Committed and actual
Awards placed show as committed immediately, so the budget reflects decisions rather than the timing of supplier paperwork.
Aggregated upward
Changes get folded into the parent award, so which modification is underfunded is a question requiring investigation.
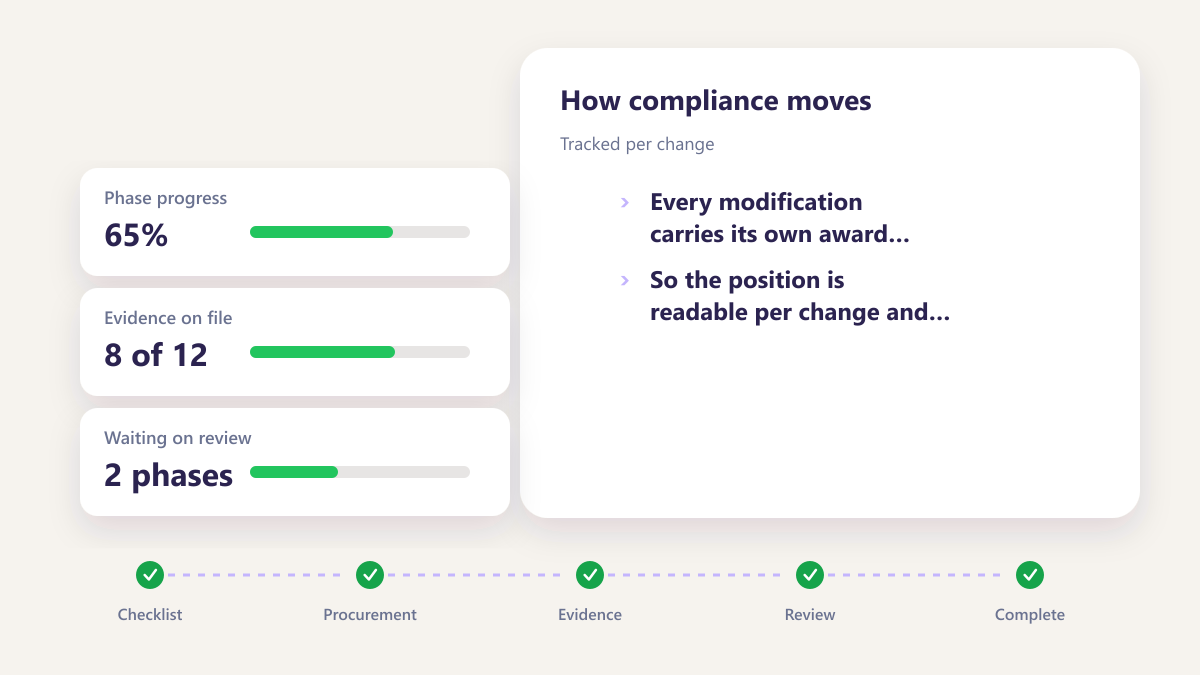
Tracked per change
Every modification carries its own award and funded figures, so the position is readable per change and in total.
A monthly exercise
A finance spreadsheet and the award records disagree, and reconciling them is recurring work nobody planned for.
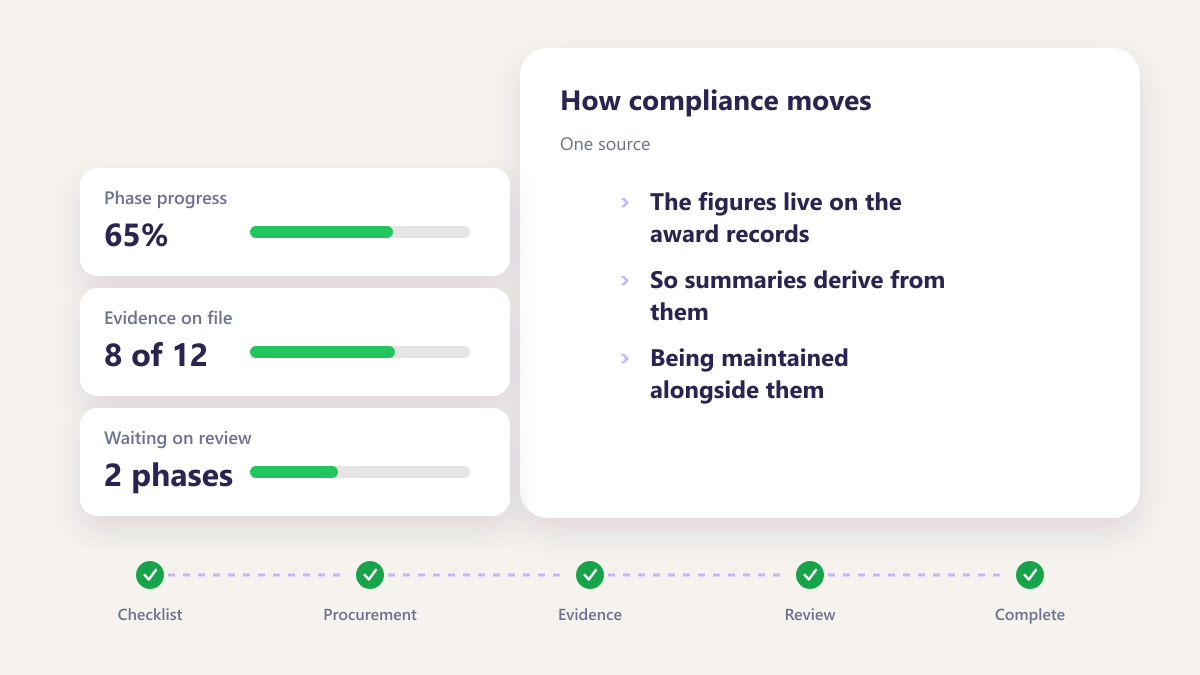
One source
The figures live on the award records, so summaries derive from them rather than being maintained alongside them.
Each answering a different question
Each answering a different question
What was agreed for this award or modification, independent of funding.
- Award amount
- Funded amount
- The gap
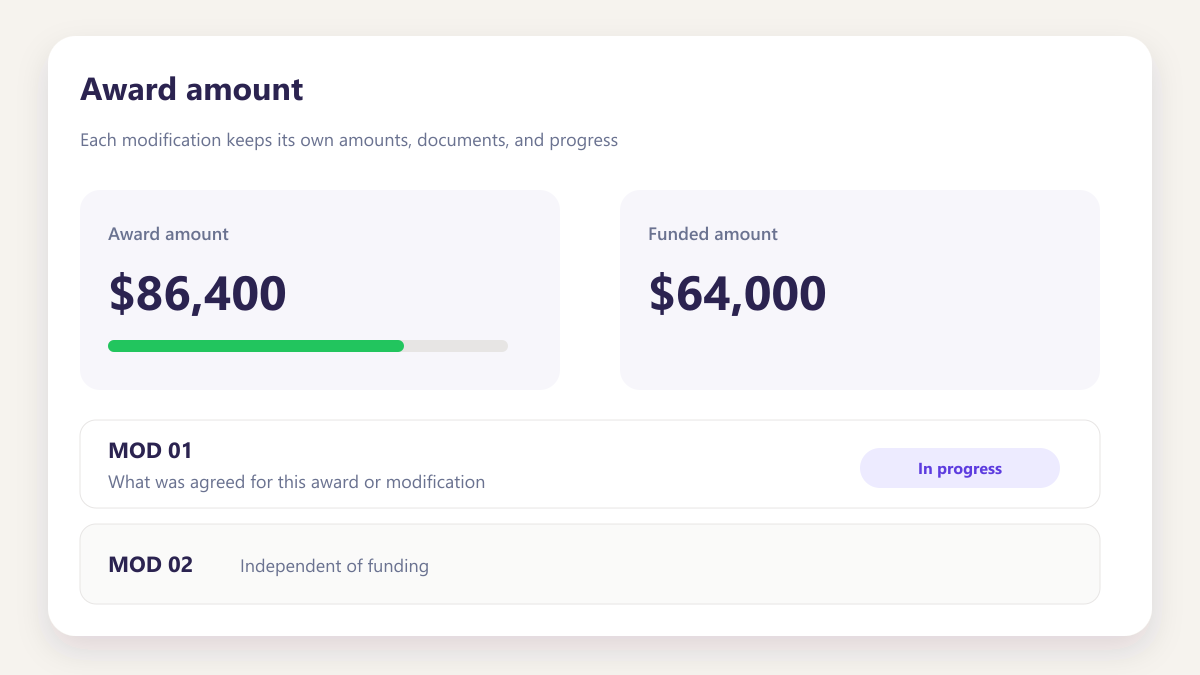
Award amount
What was agreed for this award or modification, independent of funding.
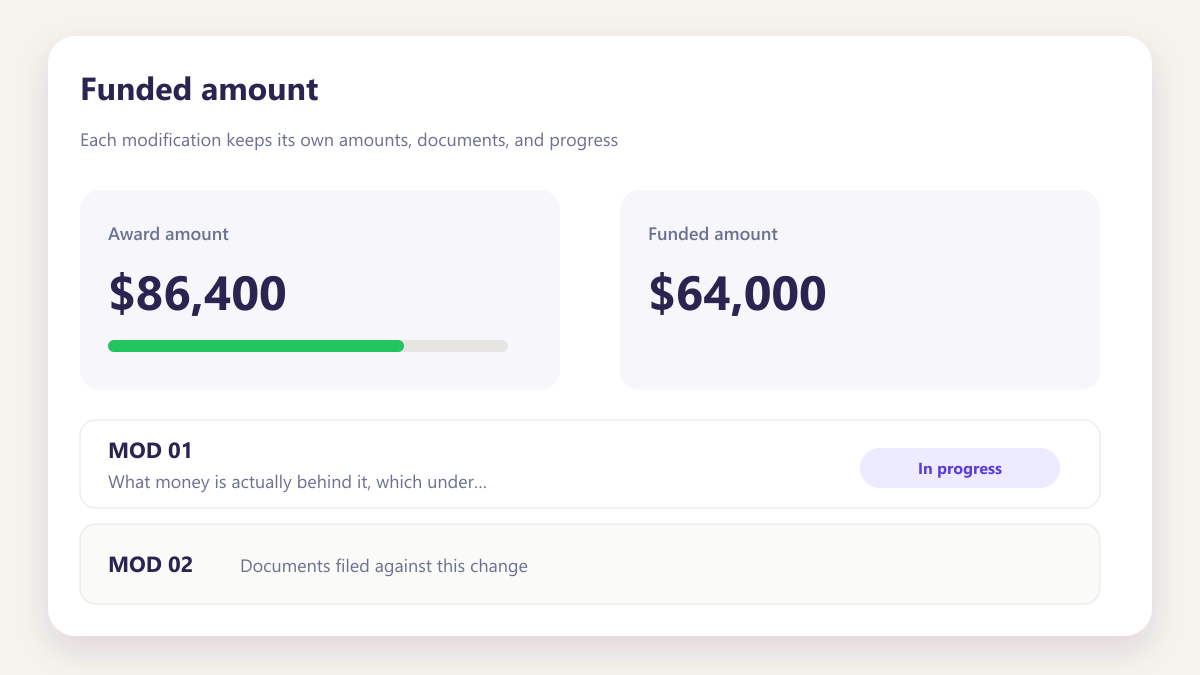
Funded amount
What money is actually behind it, which under incremental funding is often less.
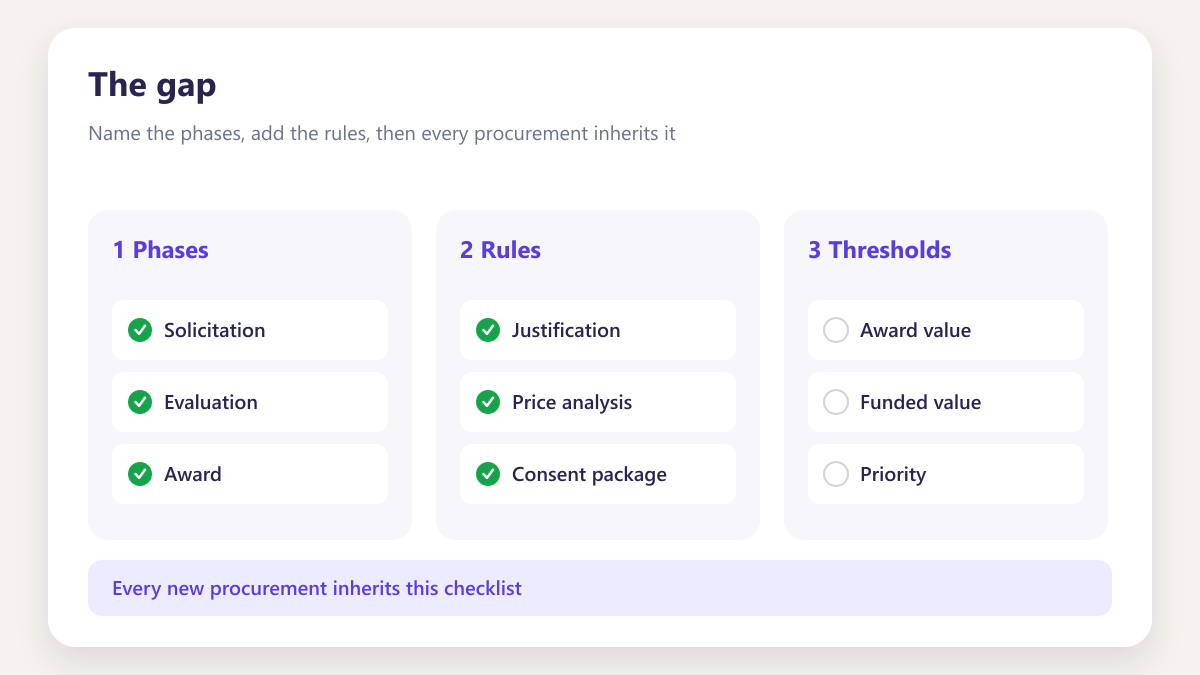
The gap
The difference, visible per modification rather than calculated when somebody asks.
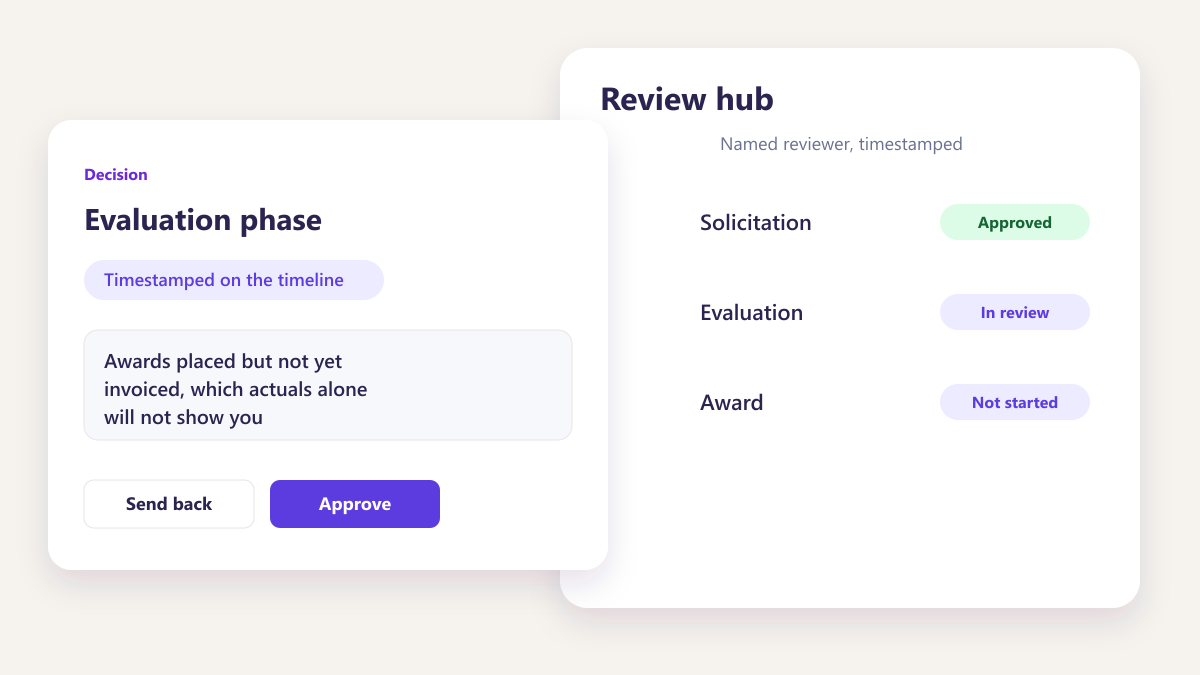
Committed spend
Awards placed but not yet invoiced, which actuals alone will not show you.
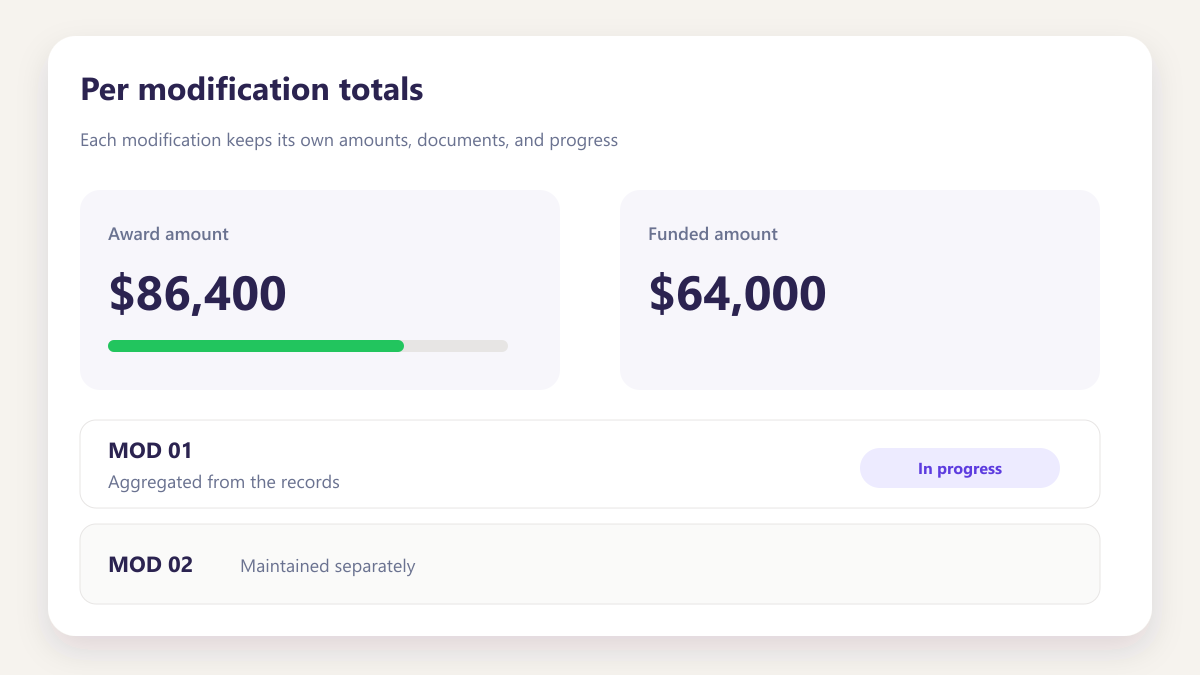
Per modification totals
Aggregated from the records rather than maintained separately.
Progress against funding
How far the work has gone relative to what has been funded for it.
Where the funding picture goes quiet
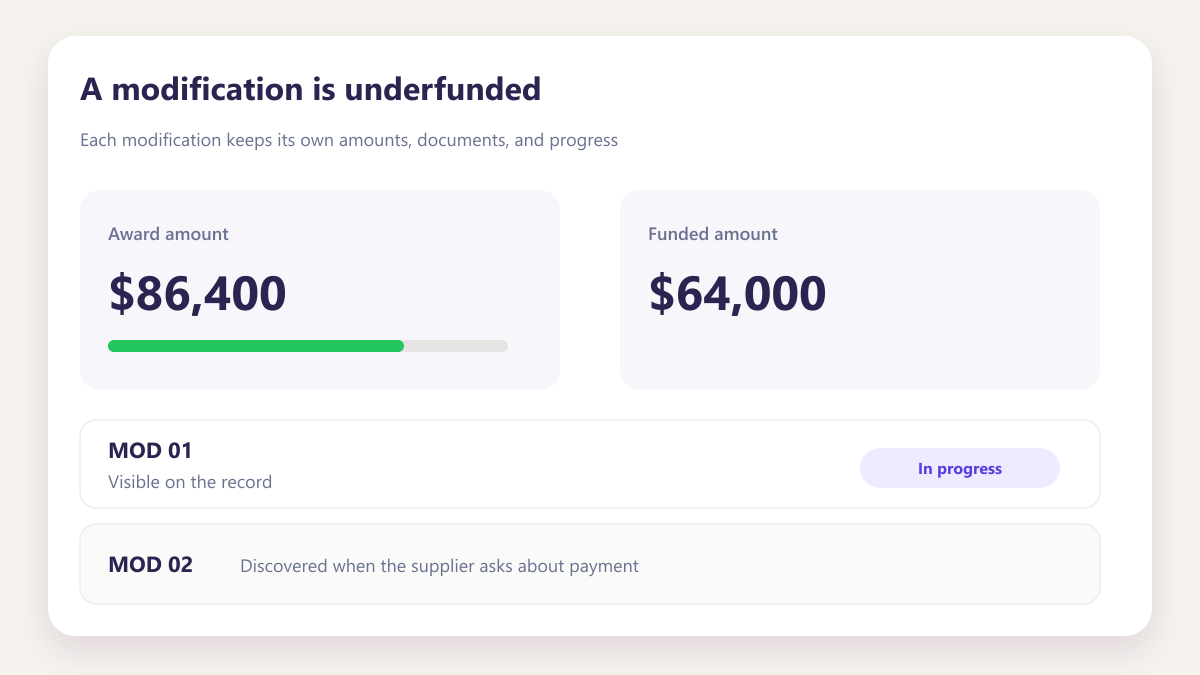
A modification is underfunded
Visible on the record rather than discovered when the supplier asks about payment.
Learn more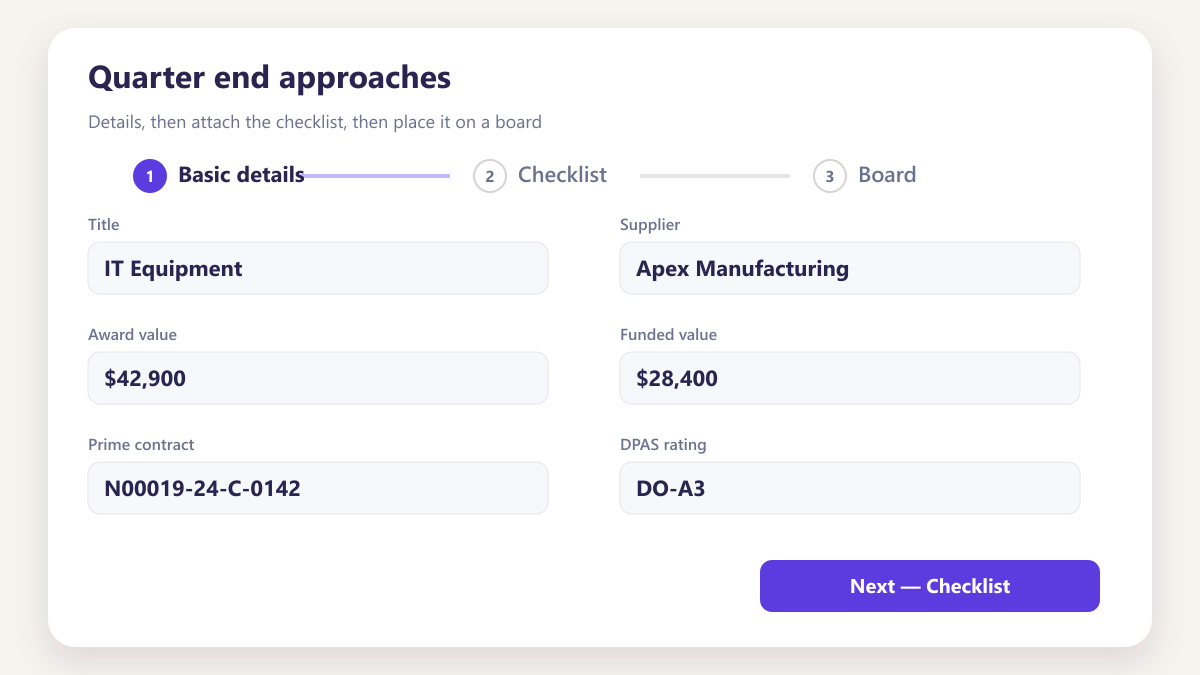
Quarter end approaches
Committed spend visible alongside actuals rather than a budget that looks healthier than it is.
Learn more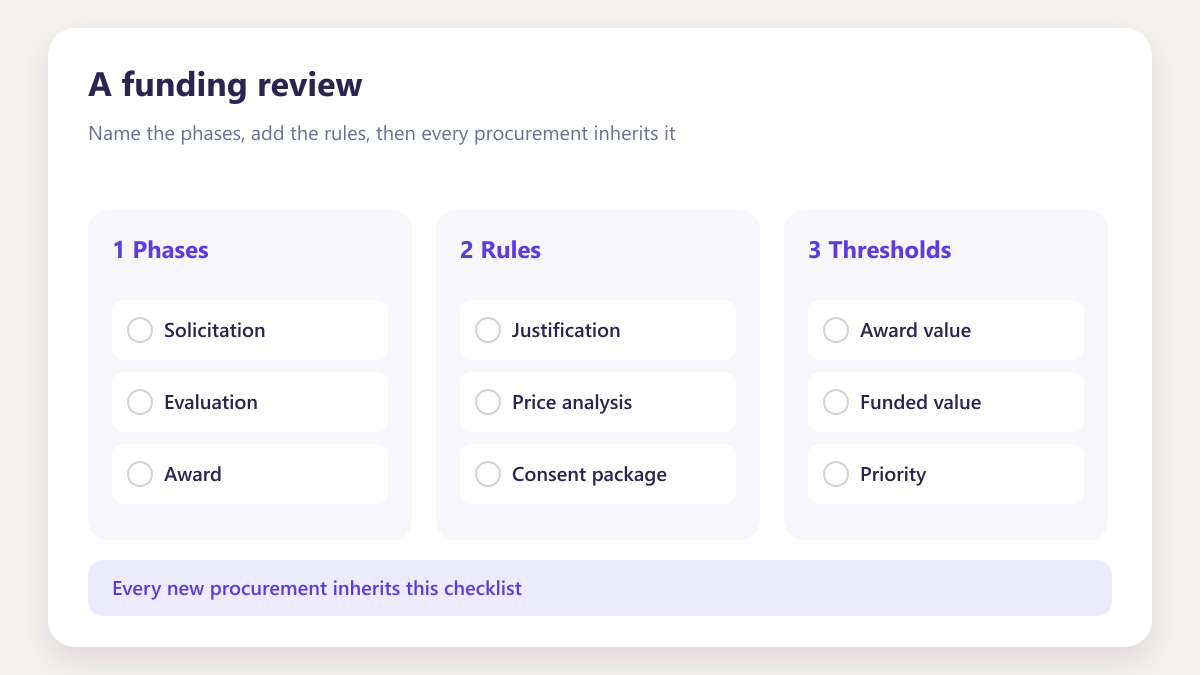
A funding review
Award against funded readable per modification without a reconciliation exercise first.
Learn more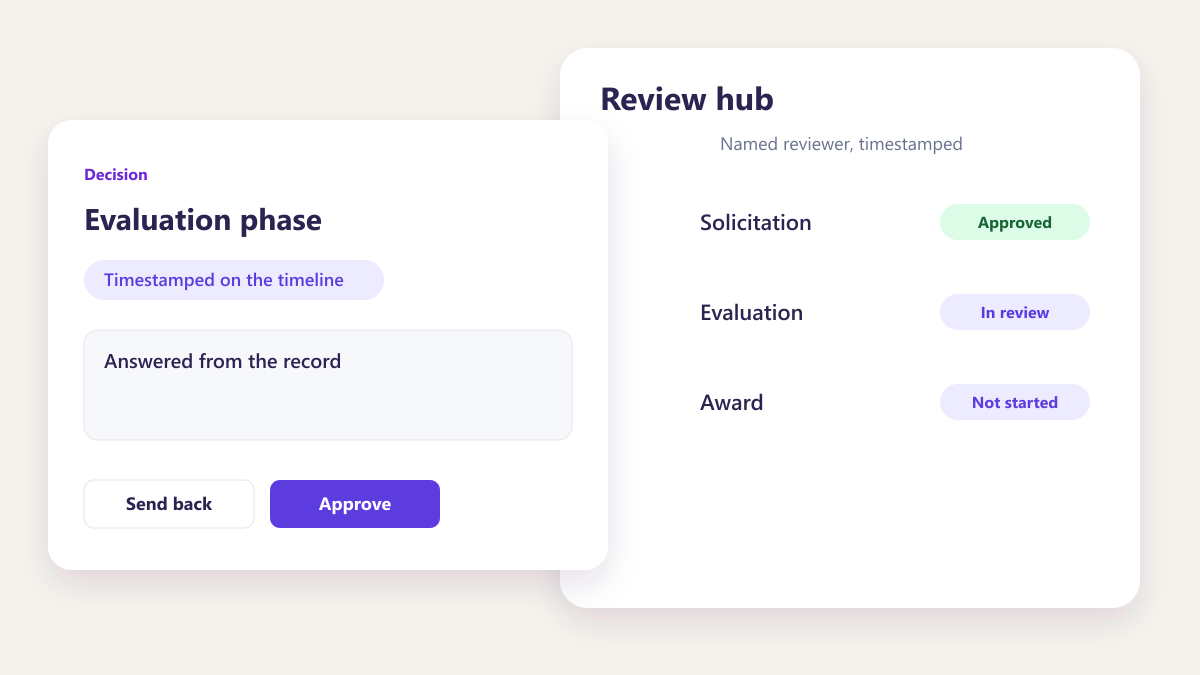
A program manager asks about headroom
Answered from the record rather than from a spreadsheet that may be a week out of date.
Learn more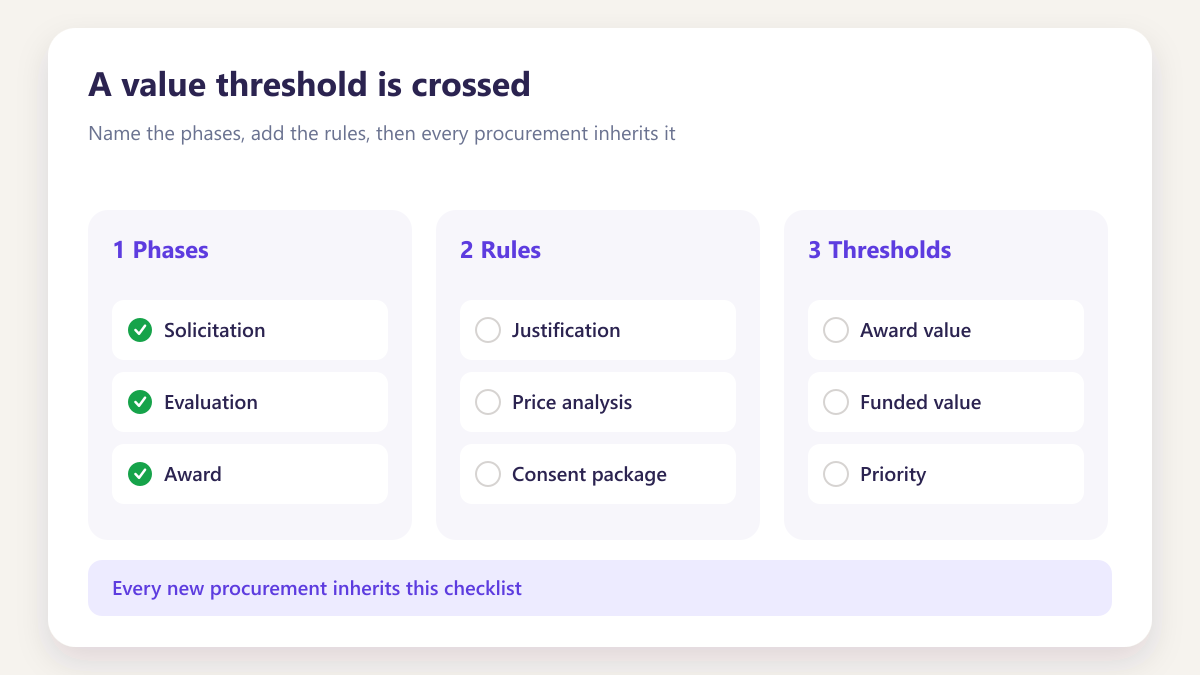
A value threshold is crossed
Finance is routed the phase automatically because the rule fires on the award amount.
Learn more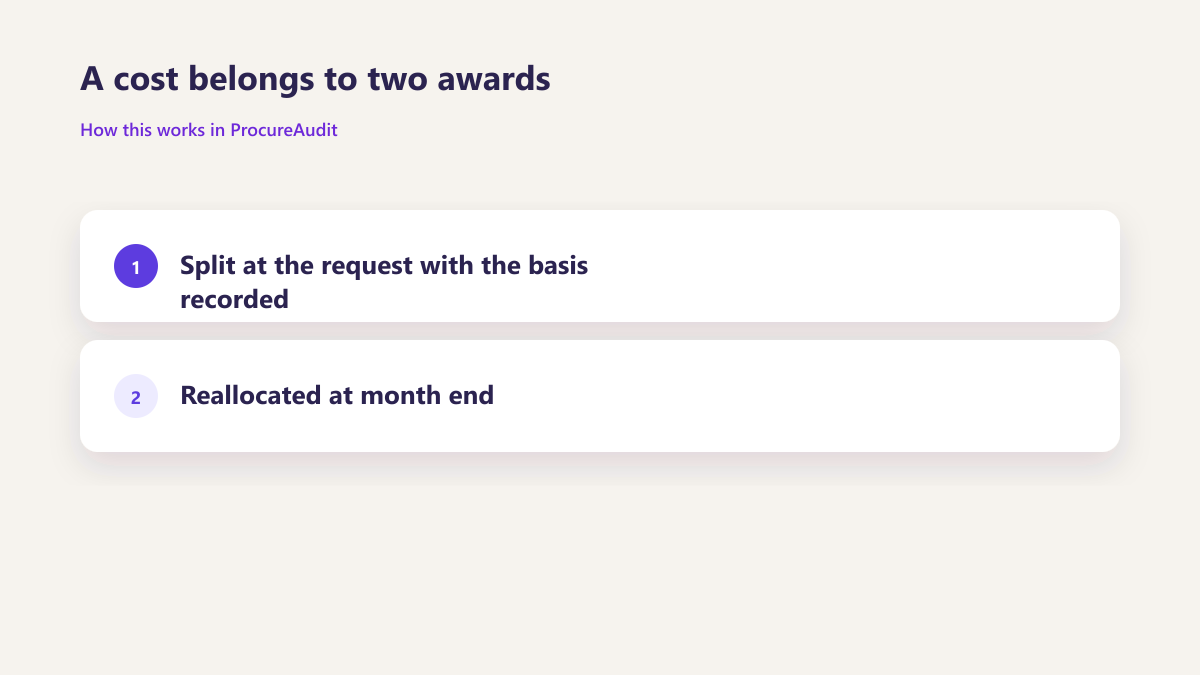
A cost belongs to two awards
Split at the request with the basis recorded rather than reallocated at month end.
Learn moreQuestions from finance leaders
What is the difference between award and funded amounts?
Why track them per modification?
Can we see committed spend before invoices arrive?
Does this replace our finance system?
Do we still need a reconciliation spreadsheet?
Can finance review specific phases?
How does this help at a funding review?
Other sectors and roles worth reading
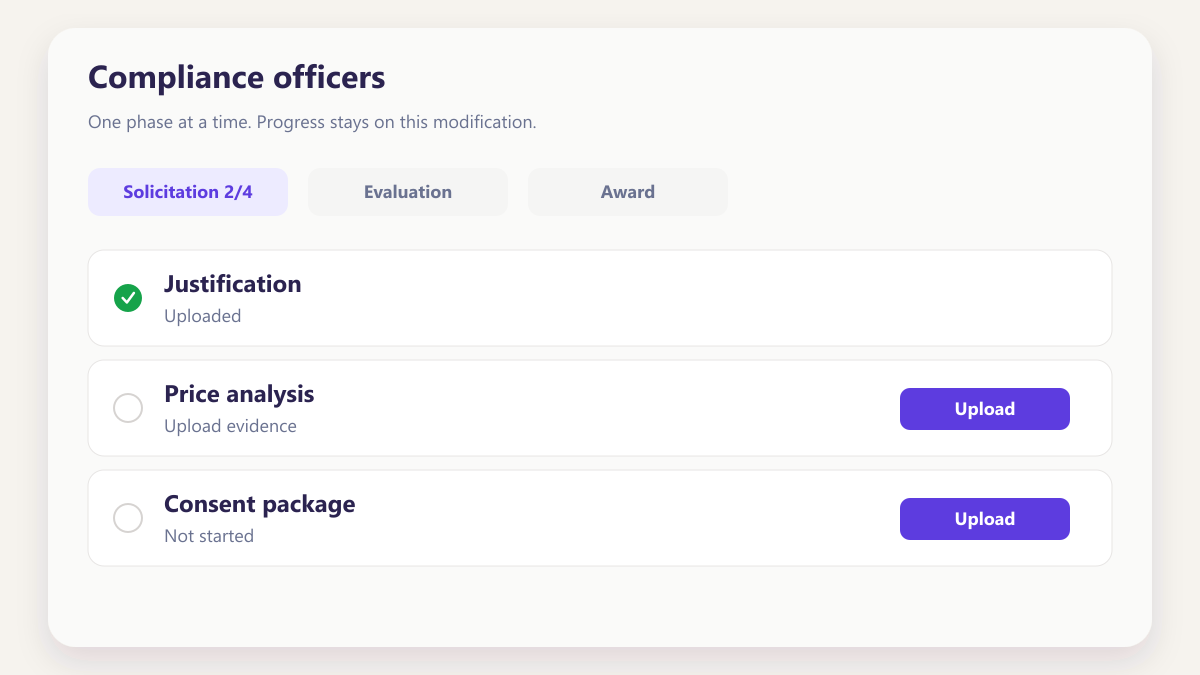
Program managers
Subcontract progress across a program without chasing individuals.
Learn more
Healthcare and life sciences
Federally funded purchasing where money carries conditions.
Learn moreBring an award with incremental funding
We will show what holding award and funded amounts separately would have made visible, and when.
Book a demo